Your Money Can Grow Itself (Yes, Really)
Here's a wild fact: if you start saving now, even small amounts, your money can basically snowball into a small fortune by retirement — without you lifting a finger after you invest it. That's the magic of compound interest: you earn interest on your money, then you earn interest on that interest, and it keeps stacking. Think of it like a snowball rolling downhill — it starts tiny, but the longer it rolls, the bigger it gets, and it picks up speed the whole way.
The Formula Behind the Magic
To estimate what your savings will be at any age, use this basic formula:
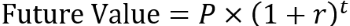
Don't worry, this isn't a math class flashback. You just need three things:
P = How much you're saving (whether it's a one-time chunk or a regular contribution)
r = Your expected annual return (historically the stock market averages 7–8%, or closer to 6% once you adjust for inflation)
t = How many years you're letting it grow
That's it. Plug those in, and time does the heavy lifting.
Let's Make This Real
Say you're 20 years old and planning to retire at 65 — that's 45 years of growth.
💸 If you save just $50 a month ($600/year) and get a 7% average return, you'd have over $150,000 by the time you retire. From $50 a month - that's less than a few takeout orders.
Here's the part that should blow your mind: because you started in your 20s, your money has over 40 years to compound. That means most of that $150K isn't even money you put in — it's growth the market handed you for free, just for starting early. Time is doing more work than your wallet is.
The Takeaway: Starting at 20 instead of 30 isn't a small head start — it's the difference between a snowball and an avalanche.
What You Actually Need to Plug In:
Want to run your own numbers? You just need:
Current age — how old you are right now (e.g., 20)
Retirement age — when you want to clock out for good (usually 65–67)
Monthly contribution — even if it's just $25 from a part-time job or internship, it counts
Rate of return — 7% is the standard go-to assumption for a stock-heavy index fund
Bottom Line:
You don't need to be rich to start. You need to start. The earlier you begin, even with pocket change, the more time your money has to work harder than you do.
